Incorporation relief – Remember to claim it
When a sole trader transfers their business to a limited company, a chargeable gain may arise on the assets transferred. As the connected person rules apply, the gain is calculated…
When a sole trader transfers their business to a limited company, a chargeable gain may arise on the assets transferred. As the connected person rules apply, the gain is calculated…
The Property 118 Tribunal case concerned whether Scheme Reference Numbers (SRNs) issued in respect of two sets of arrangements were validly issued. The arrangements in question – the SIS and…
A company tax return must be filed no later than 12 months after the end of the accounting period to which it relates. However, the corporation tax for that period…
Many people are taking on a side hustle to make ends meet. This can take various forms, such as selling items online, providing services or creating content. You may need…
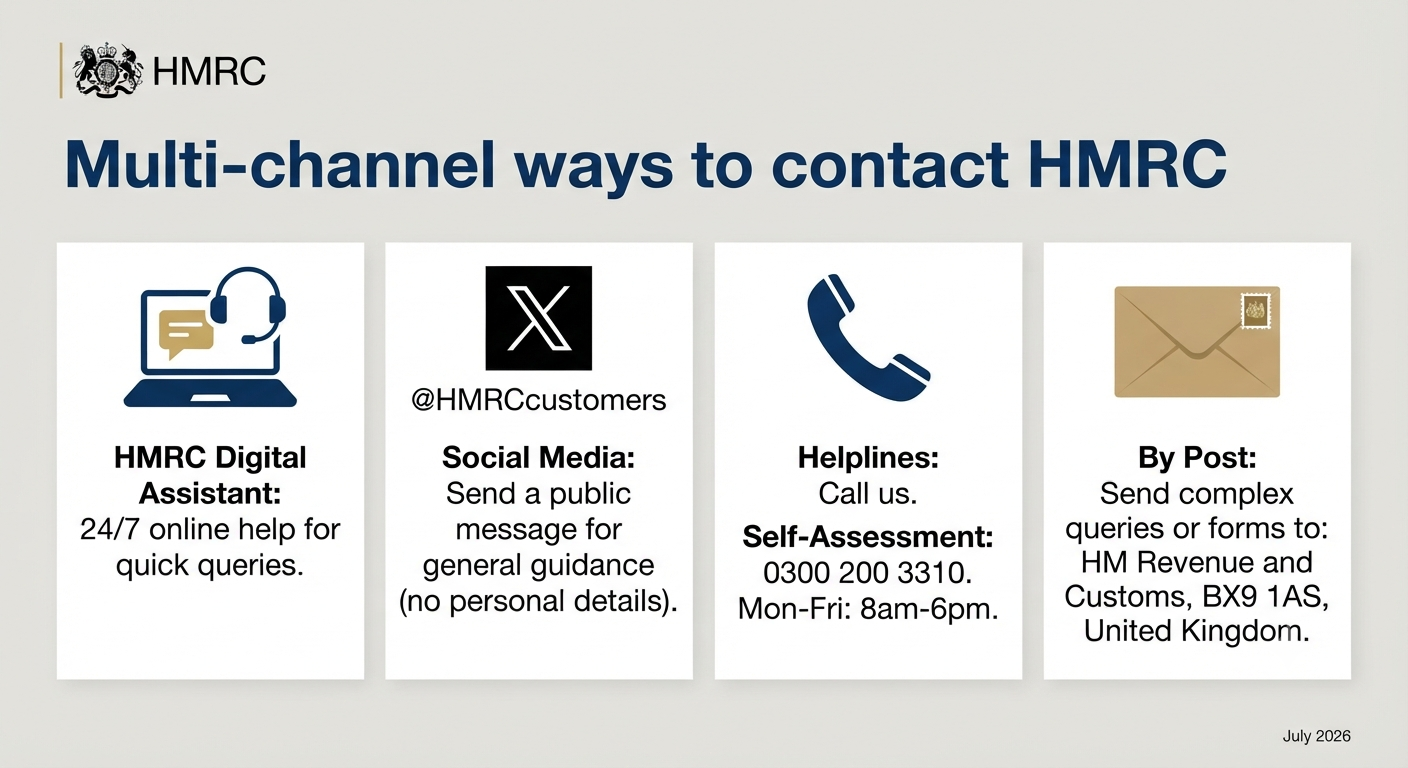
Contacting HMRC A taxpayer may need to contact HMRC if they have a query about their tax affairs. There are various ways in which this can be done. HMRC’s digital…
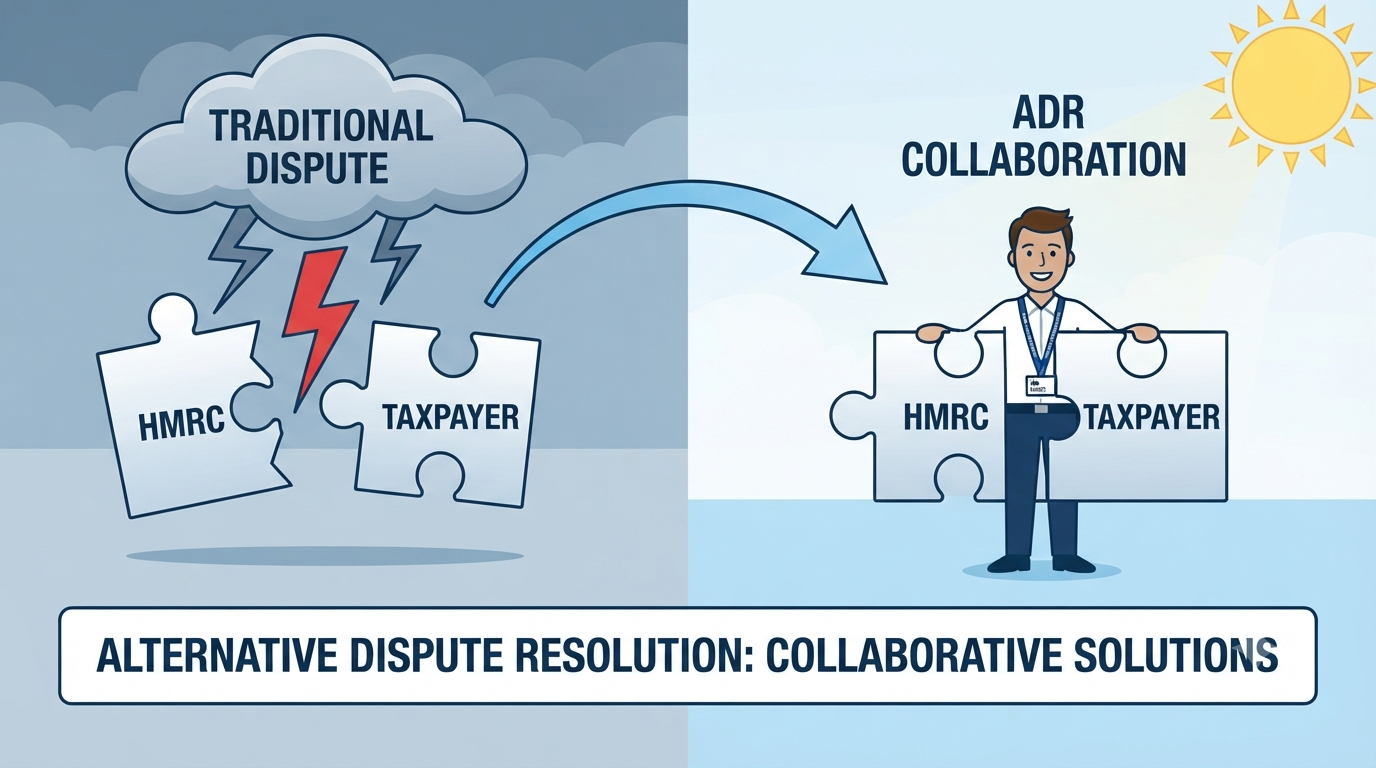
The first indication a taxpayer may receive that they are the subject of a tax enquiry or investigation is a letter from HMRC, often headed ‘Notice of enquiry under Section…
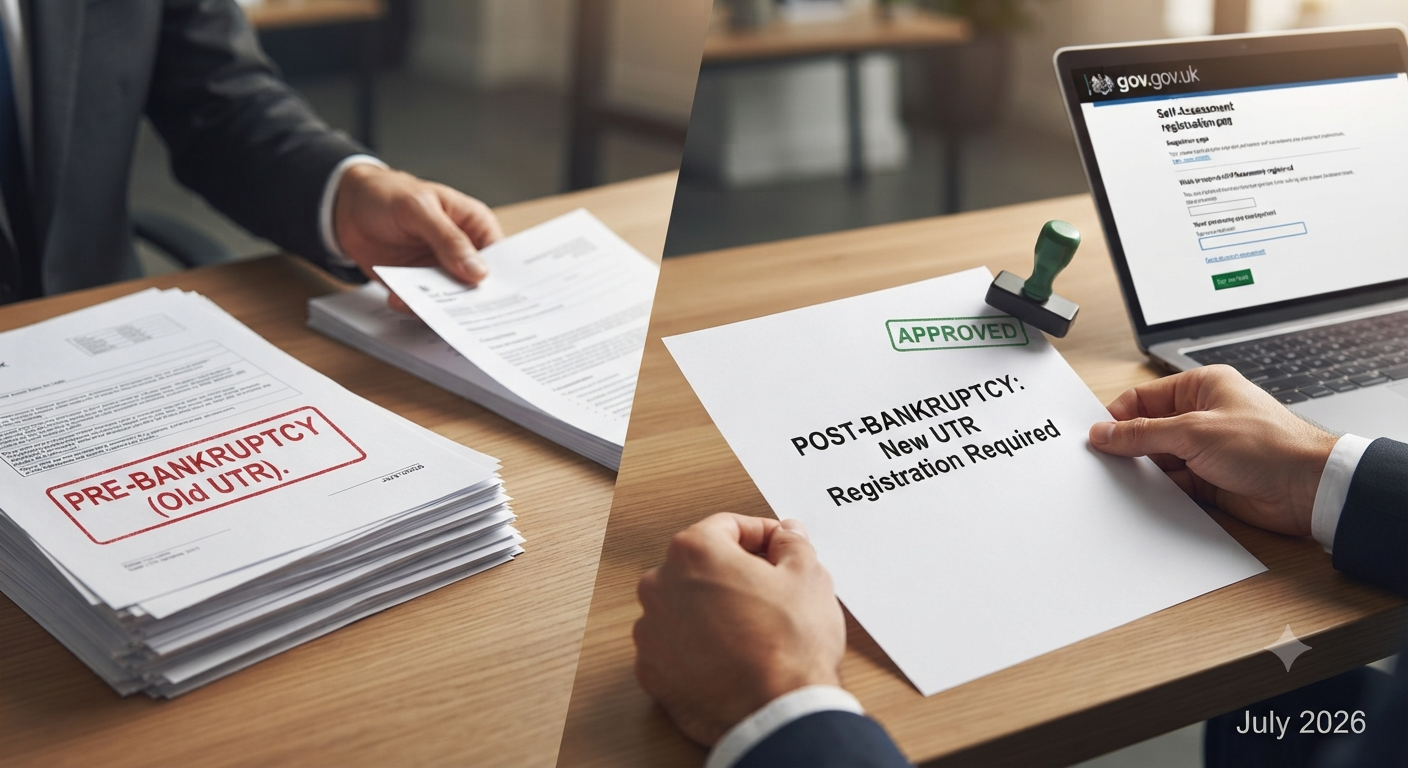
Where a taxpayer has been made bankrupt, their Unique Taxpayer Reference (UTR) expires at the end of the tax year in which they were made bankrupt. They cannot use that…
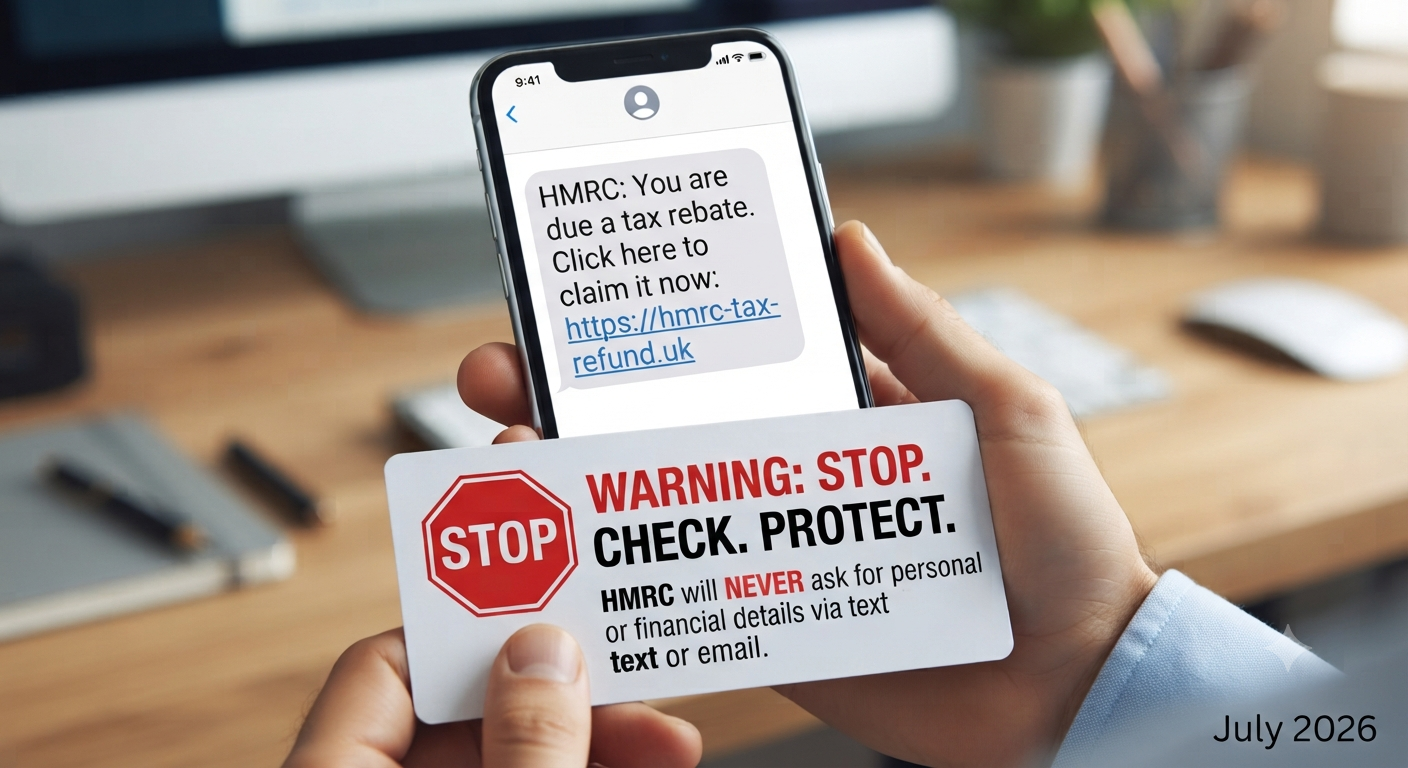
HMRC use a range of communication methods, as do fraudsters. Consequently, it can be difficult to be certain that a call, email, letter or text which seems to come from…