Interest relief – Mixed portfolios and mixed-use properties
The way in which an unincorporated landlord receives tax relief for interest and finance costs depends on whether or not the property is a residential property. Relief for interest and…
The way in which an unincorporated landlord receives tax relief for interest and finance costs depends on whether or not the property is a residential property. Relief for interest and…
Where a personal company is run from the director’s home, the payment of rent by the company for the use of the space can be a handy way of extracting…
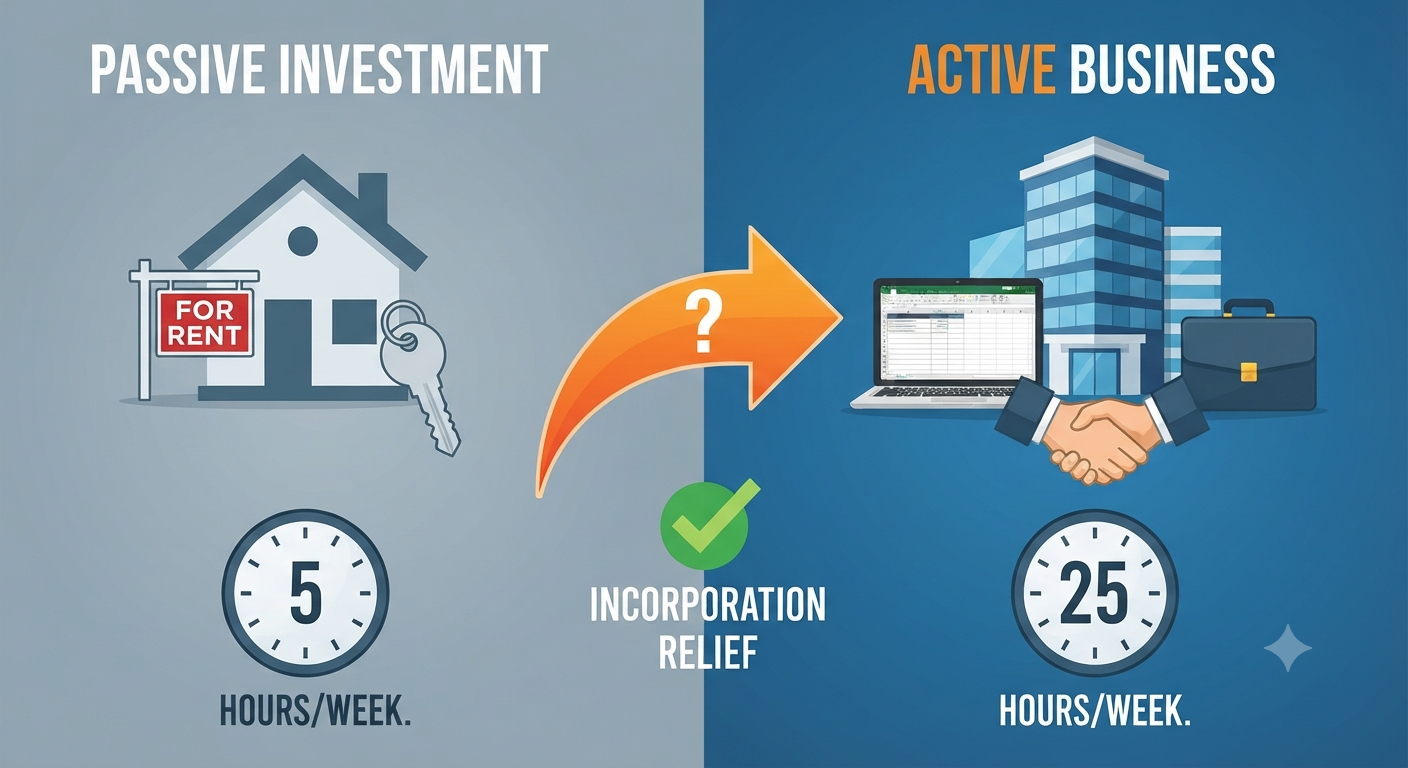
Incorporation relief is a valuable relief that allows landlords to postpone the capital gains tax bill that may otherwise arise when transferring an unincorporated property business to a limited company.…
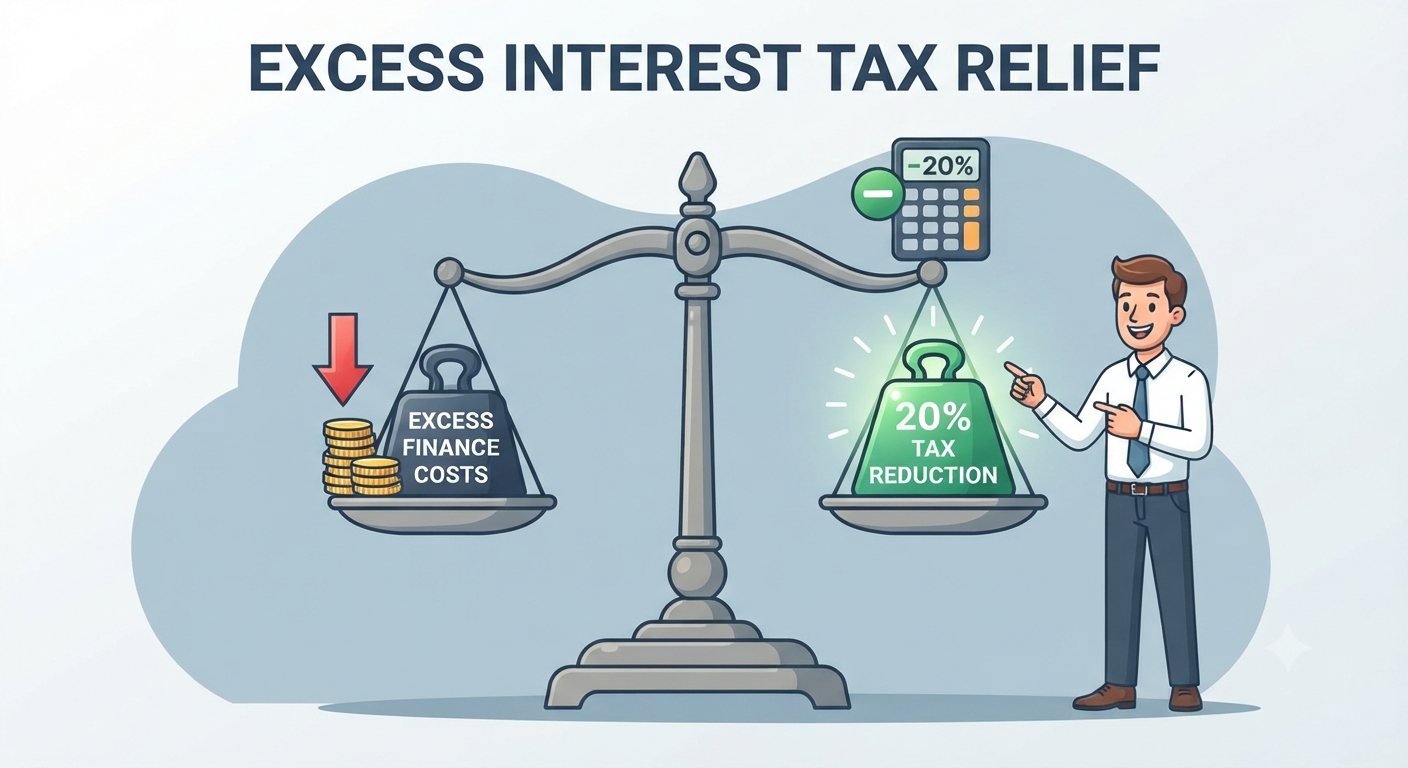
Landlords running an unincorporated property business obtain relief for interest and finance costs incurred in relation to residential lets (including holiday lets) as a tax reduction. The tax reduction is…
The cash basis is the default basis of accounts preparation for landlords with annual rental income of £150,000 or less running unincorporated property businesses. Under the cash basis, income is…

A landlord will need to consider whether it is better to pass on an investment property during their lifetime or on their death. Here, we look at the associated tax…

As for unincorporated trading businesses, the cash basis is the default basis of accounts preparation for landlords running an unincorporated property business. However, unlike traders, landlords can only use the…

Where a business is run through a personal or family company, the directors/shareholders will need to extract profits if they are to be used personally. There are various ways in…

The property allowance is essentially an additional personal allowance for income from property. It allows individuals to enjoy property income of up to £1,000 each tax year free of tax…